Verifone has been making card machines since 1981 and supplies terminals to many of the UK’s biggest payment processors. If you’ve tapped a card in a UK shop, there’s a good chance it was a Verifone device – even if another brand’s name was on it.
We rate Verifone 6.9 out of 10. The hardware is solid and widely supported, from countertop terminals to the new Android-based Victa range. But most UK businesses don’t deal with Verifone directly – you get their terminals through acquirers like Worldpay, Barclaycard, or Elavon, making the pricing completely opaque until you request a quote.
FREE QUOTE COMPARISON
Compare Merchant Account Quotes from Trusted Suppliers
✓ Compare card processing fees side by side
100% free • No obligation • Takes under 2 minutes
This review covers Verifone’s UK card machine range, how pricing works through acquirers, their direct payment services arm, and how the hardware compares to modern PAYG alternatives like SumUp and Square.
- 45 years making card machines - Verifone has built terminals since 1981 and reaches most UK merchants through acquirers such as Barclaycard, Worldpay and Elavon rather than selling direct
- No published UK prices - every product page on Verifone’s UK site routes to Contact Sales, so the terminal price, card rates and contract all come from your acquirer’s quote
- New Victa range alongside older models - Victa Mobile and Victa Portable are Android terminals with 6.7-inch screens, while the V200c, V240m, T650p and P400 are still listed
- Security certification depends on the model - Verifone’s spec sheets list PCI PTS 5.x for the older terminals and 7.x for the Victa range
- Polarised reviews - 3.4 out of 5 on Trustpilot from 395 reviews, with 75% five-star and 18% one-star, the one-star reviews mostly about settlement delays and support
- Price
- Quote via your acquirer (no published UK prices)
- Best for
- High-volume businesses using acquirer partners
- Secure hardware: PCI PTS 5.x on the established range, 7.x on Victa
- Sold through many UK acquirers, so you can compare quotes on the same terminal
- P400 PIN pad and Android terminals work alongside an existing till
- No published pricing - rates entirely dependent on your acquirer
- Trustpilot reports of settlement delays and account freezes without warning
What Verifone Offers
Verifone is primarily a hardware manufacturer supplying card terminals to UK acquirers. They also offer direct payment services including an ecommerce gateway and omnichannel platform.
Verifone operates in two distinct ways in the UK market. First, as a hardware manufacturer – supplying card terminals to acquirers like Worldpay, Barclaycard, Elavon, and Global Payments, who then lease or sell them to merchants. Most UK businesses using Verifone hardware don’t have a direct relationship with Verifone at all.
Second, as a payment services provider – offering its own merchant services, payment gateway, and omnichannel platform directly to businesses. This dual role creates confusion: Verifone the hardware maker has an excellent reputation, but Verifone the payment processor gets mixed reviews for customer service and settlement delays.
On the hardware side, Verifone’s spec sheets list PCI PTS 5.x approval for its established terminals and 7.x for the newer Victa range, and its PIN pads and Android terminals are built to work alongside an existing till. The payment services side adds an ecommerce gateway (hosted, component, or API integration), Klarna QR support, and omnichannel reporting.
Card Machines
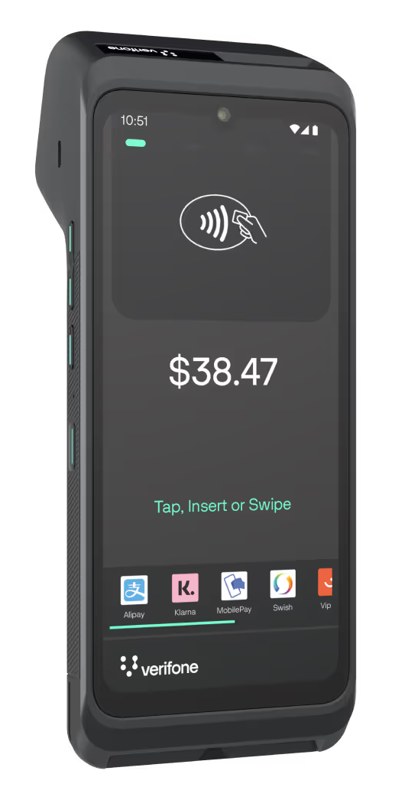
Verifone’s UK range now leads with the Victa series, and the older V200c, V240m, T650p and P400 are still listed. None has a published UK price: every product page routes to Contact Sales, and the price comes from the acquirer that supplies the terminal.
| Model | Type | Display | Connectivity | PCI PTS |
|---|---|---|---|---|
| Victa Mobile | Android handheld with barcode scanner | 6.7-inch touchscreen | 4G, Wi-Fi, Bluetooth | 7.x |
| Victa Portable | Android portable with printer and barcode scanner | 6.7-inch touchscreen | 4G, Wi-Fi, Bluetooth | 7.x |
| Victa Reader | Bluetooth card reader for iOS and Android phones | None | Bluetooth | 7.x |
| V200c | Countertop with printer | 2.8-inch colour | Ethernet, dial-up, optional Wi-Fi | 5.x |
| V240m | Portable with printer | 3.5-inch touchscreen | 3G, Wi-Fi, Bluetooth | 5.x |
| T650p | Android portable | 5.5-inch touchscreen | 4G, Wi-Fi, Bluetooth | 5.x |
| P400 | PIN pad for an existing till | 3.5-inch touchscreen | Ethernet, USB | 5.x |
All of them take contactless, mobile wallets and chip and PIN. The V240m is a portable with a built-in printer and a field-replaceable battery, a common choice for table service in restaurants and cafes. Note that its mobile connection is 3G, not 4G, so check signal and network support with your acquirer if you plan to use it away from Wi-Fi.
The T650p and the Victa terminals run Android, so apps such as loyalty, stock or POS tools can sit on the payment device itself. The P400 connects to an existing POS system as a dedicated PIN pad, keeping card entry separate from your main till.
Acquirers sell or rent Verifone terminals on their own terms, so compare rental against purchase and watch for bundled contracts that inflate the total cost. Because so many acquirers supply the same Verifone models, you can take quotes on the same terminal from several of them, which you cannot do with closed systems like Square or Clover.
Pricing and Fees
Verifone doesn’t publish UK transaction rates or hardware prices. Your acquirer sets both, along with any monthly and compliance fees.
| Cost | What to expect |
|---|---|
| Card transaction rates | Set by the acquirer; see the Barclaycard example below |
| Terminal (purchase or rental) | Quote only; Verifone publishes no UK prices |
| PCI compliance fee | Set by the acquirer; Barclaycard sets its PCI DSS management fee in your contract |
| Chargeback handling | Set by the acquirer |
| Early termination | Acquirer-dependent |
This is the fundamental issue with Verifone: you can’t compare prices until you get a quote. The transaction rate, contract length, and monthly fees are all set by whichever acquirer supplies your terminal. The same V240m can carry a different debit rate from each acquirer. Barclaycard’s representative debit rate, for example, is 0.7% plus 3p authorisation on a £50 transaction.
For high-volume businesses (£250K+/year), ask for interchange-plus pricing rather than blended rates. This separates the card scheme fees from the acquirer’s margin and usually works out cheaper. For lower volumes, the PAYG alternatives – SumUp at 1.69% or Square at 1.75% – are simpler to compare since their rates are published.
Customer Experience
3.4/5 on Trustpilot from 395 reviews – middling and sharply polarised. Positive reviews praise hardware reliability and competitive rates. Negative reviews cite settlement delays, account freezes, and withheld funds.
Verifone’s Trustpilot profile tells a split story. Three quarters of reviewers give five stars, but 18% give one, and only 7% land anywhere in between. The 3.4/5 average is the average of two very different experiences, not a consistent middling one.
Positive reviewers highlight the hardware quality, competitive transaction rates (when sourced through the right acquirer), and long-term reliability. Some merchants have used Verifone terminals for years without issues.
The negative reviews are more concerning: settlement delays, account freezes without warning, and funds withheld with no clear explanation. One merchant wrote in July 2025 that nearly £5,000 was still unsettled after 12 days; another said in December 2024 that £14,100 had been withheld. For a small business relying on cash flow, this is devastating.
Several one-star reviewers describe support that is hard to reach or slow to fix faults, including repeated terminal replacements. Getting a terminal through an acquirer also means an application and checks, which is slower than ordering a pay-as-you-go reader online from SumUp or Square.
Pros and Cons
Enterprise-grade hardware with multi-acquirer flexibility, but opaque pricing and reports of settlement delays make due diligence essential before signing.
Verifone vs Alternatives
Verifone hardware excels for high-volume businesses using acquirers. For SMEs processing under £100K/year, PAYG alternatives like SumUp, Square, or Tide offer simpler pricing and faster setup.
| Provider | Transaction Rate | Entry Price | Contract | Trustpilot |
|---|---|---|---|---|
| Verifone | Set by acquirer | Quote only | Acquirer-dependent | 3.4/5 |
| SumUp | 1.69% | From £25 + VAT | None | 4.2/5 |
| Square | 1.75% | From £19 + VAT | None | 3.9/5 |
| Dojo | 1.2% blended (under £100K/yr) | £0 Tap to Pay on iPhone; machines from £149 (launch offer) | 12-month price lock; Tap to Pay no contract | 4.2/5 |
| Barclaycard | Quoted individually | £29 (PAYG reader) | None / 12-18 mo | Not comparable* |
*Barclaycard’s Trustpilot profile is dominated by its credit card customers rather than merchants, so its score does not measure the card machine service.
Below ~£100K/year in card turnover, PAYG providers like SumUp or Square are cheaper despite higher per-transaction rates – because you avoid contracts, rental and PCI fees. Above £100K, the lower acquirer rates on Verifone terminals start to pay back the upfront investment.
Verifone’s main advantage is choice of acquirer. Worldpay, Barclaycard, Elavon and others all supply its terminals, so you can put the same model out to several quotes. Square and Clover lock you into their ecosystems – if you outgrow them, you’re buying everything again from scratch.
Our Verdict
We rate Verifone 6.9/10 – best-in-class hardware with genuine multi-acquirer flexibility, but the opaque pricing model and settlement delay reports mean most SMEs are better served by transparent PAYG alternatives.
Best-in-class hardware with multi-acquirer flexibility, but opaque pricing and settlement delay reports mean most SMEs are better served by PAYG alternatives
How we score: 6 categories, weighted as shown. The total is the weighted average of these scores. Our review process
FREE QUOTE COMPARISON
Compare Merchant Account Quotes from Trusted Suppliers
✓ Compare card processing fees side by side
100% free • No obligation • Takes under 2 minutes
Verifone makes excellent card machines. The V240m and T650p are proven workhorses, supplied by most of the big UK acquirers and built to sit alongside a POS system, and the new Victa range brings the hardware up to date. If you’re a multi-site retailer or hospitality business processing £250K+ per year, Verifone hardware paired with the right acquirer deal can deliver genuinely competitive economics.
But for the majority of UK SMEs, the Verifone route adds unnecessary complexity. You can’t see pricing until you get a quote, setup takes days rather than minutes, and the reports of settlement delays and frozen funds are a real risk for cash-flow dependent businesses. Modern PAYG alternatives publish their rates, ship next-day, and let you start taking payments immediately. For a full comparison, see our best card machines guide or compare payment processing costs.
Related Merchant Account Guides